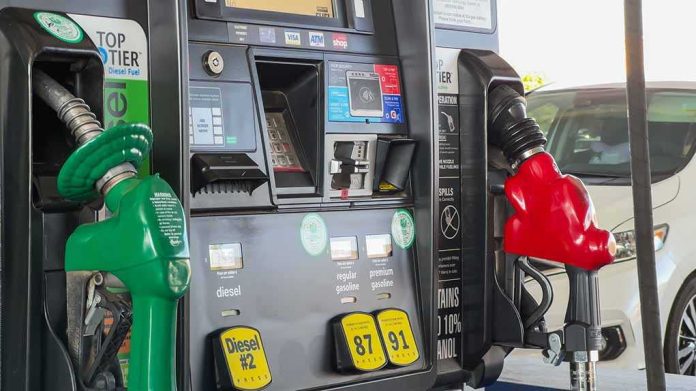
Record diesel prices are not a fluke of retail behavior but the visible edge of a structural squeeze: when geopolitics rattles refined product flows, diesel moves first, faster, and further than petrol—because the diesel market is tighter, more refinery‑dependent, and more exposed to chokepoints and sanctions.
At a Glance
- UK average diesel prices set a new record of 199.18p per litre, surpassing the prior June 2022 peak.
- Diesel reacts more sharply than petrol to global shocks because supply hinges on refining capacity and specific trade flows.
- The 2026 spike echoes 2022’s pattern: product shortages, disrupted routes, and higher refining margins drive the forecourt outcome.
- For hauliers, farmers, and off‑grid users, diesel inflation compounds wider cost pressures and can ripple through consumer prices.
What happened and why it matters
The UK’s average pump price for diesel reached 199.18p per litre, eclipsing the previous record set during the 2022 energy shock. The headline is simple; the mechanism is not. Diesel sits at the intersection of crude availability, specialized refining capacity, and international product logistics. When conflict or sanctions disturb any one of those links, diesel prices spike disproportionately because the system has less slack than motorists assume. In 2026, the same fault lines that defined 2022 reappeared: disrupted product exports, heightened risk around key maritime routes, and a scramble among import‑reliant consumers. RAC’s market monitoring captured the new high and the breaching of the 2022 watermark with precision.
Diesel’s role in the economy makes the record consequential far beyond the forecourt. Heavy goods vehicles, rail in certain corridors, agriculture, construction, and many backup generators rely on diesel or close substitutes like gasoil. A sharp diesel move bleeds into freight rates and farm input costs, and—over subsequent weeks—into shelf prices. That transmission isn’t instantaneous, but it is real; analysts and official statistics have repeatedly tied fuel spikes to swings in inflation when product markets tighten at speed.
Diesel is a product story first: the mechanism that drives records
Crude oil sets the baseline, but diesel pricing lives and dies by the availability of middle distillates from refiners. Diesel (and heating oil/jet fuel in the same cut) competes within the barrel. If refineries go offline, if maintenance overruns, or if sanctions and conflict rearrange trade flows, the world loses not “oil” in general but specific product volumes in specific places. Replaceable, but not instantly. Europe, and the UK within it, imports a meaningful share of its diesel because of structural imbalances between domestic refining configuration and road fuel demand. That dependence magnifies the effect of any squeeze on export suppliers or shipping lanes—exactly the pattern seen in 2022 and reprised in 2026 as Middle East disruption and earlier hits to Russian product exports tightened available barrels.
Two market levers do the visible work. First, refining margins for middle distillates—the extra value refiners earn above crude—expand when product is scarce; that premium gets baked into wholesale prices. Second, freight and risk premiums rise when routes are threatened or insurers price in conflict. The UK’s average crossing 199p again is the retail manifestation of those wholesale dynamics. In 2022, parliamentary research recorded the prior diesel apex near 199p; the 2026 breach tracked by RAC and reported by major outlets shows the same physics operating under new geopolitical stress.
How we got here: the repeating playbook from 2022 to today
In mid‑2022, Russia’s invasion of Ukraine and ensuing sanctions fractured the European diesel supply map. Refiners that once relied on steady Russian vacuum gasoil or diesel had to re‑source, often at higher cost and longer haul. Simultaneously, post‑pandemic demand normalized. The result: record averages of roughly 191.5p for petrol and 199.09p for diesel in the UK that summer, with diesel’s peak arriving first and punching higher than petrol because middle distillate tightness was the dominant constraint.
The 2026 episode differs in actors but not in anatomy. Conflict in the Middle East—both a source region and a crossroads—introduces intermittent threats to crude supply and, crucially, to refinery output and product shipping through chokepoints. Traders pay up for prompt barrels; refiners capture stronger diesel cracks; wholesale screens reprice; retailers pass through with a lag. RAC’s late‑September alert flagged the approach to the old record and widespread forecourts already above that line; days later, the national average cleared it, landing at 199.18p.
Why diesel outpaces petrol in crises
Three structural features explain diesel’s outsized swings. First, diesel demand is less elastic in the short run: you can delay leisure driving more readily than a supermarket can delay a lorry run. Second, Europe’s refining slate was historically optimized for petrol; rebalancing to diesel has limits without substantial capex. Third, diesel’s global trade is more concentrated; when a few export hubs falter, alternatives are neither abundant nor immediately fungible. This is why the UK’s averages tend to crest for diesel before petrol during shocks and by a wider margin—confirmed by both market data and long‑run statistical series from 2022’s peak through the latest surge.
In practice, that means the “headline” is not mere sensationalism. A national average near £2 per litre for diesel tells you that margins and logistics are strained, and that the system is incentivizing barrels to move toward shortage—signal doing its job. While isolated forecourts can overshoot, a sustained countrywide average at a record indicates a genuine wholesale tightness rather than simple retail opportunism, a point consistent with RAC’s wholesale‑to‑retail tracking and the cross‑market corroboration by major newswires in 2026.
I see that diesel prices have hit a record high in the UK at 199.18p per litre. No doubt this will soon be passed onto us all in the shops.
Meanwhile number of UK oil refineries to produce diesel fuel now at record low…#Diesel #Fuel
— haymansafc 🌸 (@haymansafc) September 28, 2026
Implications: who feels it, how long it lasts, and what can help
Hauliers feel the hit first; diesel is a line‑item that reprices weekly. Smaller operators with thinner hedging or weaker surcharge pass‑through will struggle before larger fleets do. Agriculture and construction follow on seasonal schedules, magnifying pressures when planting or project cycles peak. Consumers encounter the effect later, via delivery fees or shelf inflation, which policymakers then chase in broader price indices. In 2022, the feedback loop was unmistakable; the 2026 spike raises the same risk profile if elevated prices persist into subsequent months.
What breaks the cycle is not a policy soundbite but more product: additional refinery runs, redirected exports, or restored safe passage on key routes. Tactical levers—transparent wholesale‑to‑retail pass‑through scrutiny, prompt release of any government‑held product where applicable, or temporary logistics facilitation—can smooth peaks at the margin. But the durable mitigation is structural: resilient refining capacity in allied jurisdictions, diversified import sources, and cleaner freight that reduces absolute diesel dependence over time. None of that resolves overnight; all of it lowers the odds that the next geopolitical shock prints a new record on UK forecourts.
How to read the next spike
When the next price alert lands, look past the pence. Ask three questions. Are diesel refining margins (the diesel crack) unusually high versus crude? Are key export hubs or transit lanes impaired by conflict, sanctions, or maintenance? And are European stock levels of middle distillates below seasonal norms? If the answers trend yes, the forecourt will follow. The 2026 breach of 199.18p per litre checks those boxes, just as the 2022 episode did. Records are symptoms; the underlying condition is a global product system that remains tight, brittle, and exquisitely sensitive to geopolitics.
Sources:
theguardian.com, oilprice.com, businessmotoring.co.uk, researchbriefings.files.parliament.uk